
Indemnity Clause Meaning: A Plain English Guide for 2026
Understand the indemnity clause meaning in your contracts. This guide explains risks, red flags, and negotiation tips for freelancers, tenants, and SMBs.
16 min read
An indemnity clause is a contract term that transfers financial risk for specific losses or damages from one party to another, making you promise to pay for the other side's potential legal problems. In many commercial contracts, that obligation can last 3 to 5 years if nobody narrows it during negotiation, which is why this small paragraph matters so much to freelancers, tenants, and small business owners.
You've probably seen it buried in a services agreement, lease, vendor contract, or software subscription. Everything looks ordinary until you hit a sentence that says you'll “indemnify, defend, and hold harmless” the other side for claims related to the agreement. That's the moment many smart people pause, reread it twice, and still aren't sure whether they're agreeing to something routine or something financially dangerous.
Usually, it's both common and risky.
The hard part about indemnity clause meaning isn't the dictionary definition. It's understanding what the clause can force you to pay for, when those costs start, and how to push back without blowing up the deal. For most individuals, the main issue isn't legal theory. It's whether one paragraph could turn a manageable project or lease into a bill for lawyers, settlements, or damages that should never have landed on your side in the first place.
Table of Contents
- What Is This Clause Buried in My Contract
- How an Indemnity Clause Actually Works
- The Three Flavors of Indemnity From Mild to Toxic
- Real-World Examples in Your Contracts
- Indemnity Red Flags and How to Spot Them
- How to Negotiate a Safer Indemnity Clause
- Frequently Asked Questions About Indemnity Clauses
What Is This Clause Buried in My Contract
A freelancer lands a solid client, agrees on scope, and is ready to start. Then one paragraph says the freelancer must “indemnify, defend, and hold harmless” the client for claims tied to the project. That is the point where a routine contract can turn into a money-risk problem.
In plain English, the indemnity clause meaning is simple. You are agreeing to pay if certain problems land on the other side and the contract says those problems are yours to cover. Sometimes that is fair. If you used unlicensed photos in a campaign, you should expect to be on the hook for that. The trouble starts when the clause is drafted so broadly that you are covering losses you did not really cause.
That matters more to a freelancer, tenant, or small business owner than many legal guides admit. Large companies often treat indemnity as one more risk-allocation tool. An individual signing the same language may be risking savings, future income, or an insurance claim.
A practical test helps. Ask two questions: what event triggers this clause, and whose mess am I really agreeing to pay for?
If the answer is fuzzy, slow down.
People often skim indemnity language because the paragraph looks dense and repetitive. They focus on rate, timeline, deposit, renewal terms, or who owns the work. Then a complaint arrives from a customer, landlord, platform user, or copyright owner, and this buried clause becomes the most expensive sentence in the contract.
Here is what usually decides whether the clause is reasonable or dangerous:
- The trigger: Is it limited to your breach, negligence, or IP infringement, or does it reach anything “arising out of” the contract?
- The cost: Are you covering only proven losses, or also legal fees, settlements, investigations, and other claimed expenses?
- The control: Does the other side get to choose the lawyer and run up the bill while you pay?
Before you sign, it helps to spot hidden traps in agreements the same way you would check a lease for repair liability or a client agreement for late-payment terms. Indemnity belongs on that short list. It is often buried in boilerplate, but it can shift real financial risk onto the person least able to absorb it.
How an Indemnity Clause Actually Works
The simple version
The cleanest analogy is this. Your friend borrows your car, gets into a minor accident, and you had previously promised to cover your friend's liability if anything went wrong. That promise is the basic logic of indemnity. One person agrees to absorb the cost that would otherwise hit someone else.
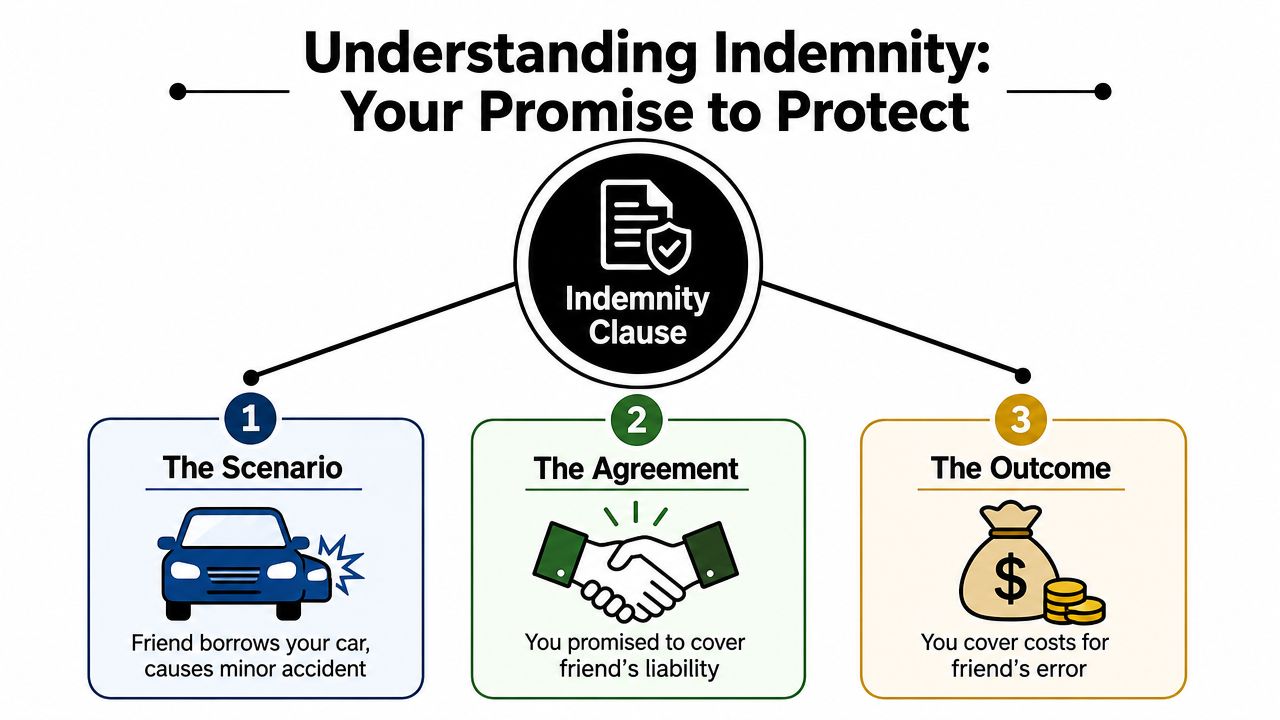
In contracts, the party making that promise is the indemnifying party. The protected party is the indemnified party. Once you know those two roles, most indemnity language becomes easier to decode.
What matters next is the trigger. A good clause names specific events. A weak or aggressive clause uses broad wording that sweeps in almost anything tied to the contract. Commercial guidance from Icertis explains that an indemnity clause often works as a risk-transfer mechanism that allocates third-party claims, defense costs, settlements, and damages to the indemnifying party, and that many clauses also include a separate duty to defend according to Icertis on indemnification scope and defense obligations.
Here's the practical takeaway. Indemnity isn't just about reimbursing a loss after the dust settles. It can move the whole financial mess to your side.
Why defense language changes everything
The phrase people miss most often is defend.
If a clause says only that you must indemnify, that often points toward paying covered losses after they exist or after the claim is resolved. If the clause says you must defend, you may have to start paying for lawyers and litigation management much earlier.
That timing issue is what catches small businesses off guard. Cash leaves before fault is clear. Even a weak claim can become expensive just because someone has to respond, investigate, and manage counsel.
A useful way to read the clause is to break it into pieces:
- Indemnify means compensate for covered loss.
- Defend means handle or fund the response to a claim.
- Hold harmless usually reinforces protection for the other side.
The dangerous version isn't always the one with the harshest tone. It's the one that starts the meter running before anyone knows who was actually at fault.
If the contract doesn't clearly define the trigger, covered losses, and claim procedure, you're not looking at a routine sentence. You're looking at a blank check with legal formatting.
The Three Flavors of Indemnity From Mild to Toxic
What broad intermediate and limited usually mean
A freelance designer signs a client contract, skims the indemnity clause, and assumes it just means “don't cause problems.” Six months later, the client gets sued over a campaign that used the client's own copy and approvals, and the designer is asked to cover the legal bill too. That is the difference between a limited clause and a broad one.
In U.S. contracts, indemnity language usually falls into three buckets: broad, intermediate, and limited. You do not need to memorize legal labels. You need to spot how much risk the clause pushes onto you, especially if you are one person or a small business without a legal budget sitting in reserve.
| Indemnity Type | What It Covers | Your Risk Level |
|---|---|---|
| Broad | Shifts wide responsibility to you, sometimes for claims only loosely connected to the deal, including problems you did not directly cause | Very high |
| Intermediate | Puts substantial responsibility on you, but stops short of the broadest version | High |
| Limited | Restricts responsibility to losses directly caused by your own breach, negligence, or misconduct | Lower and usually more reasonable |
For a solo consultant, tenant, or small agency, limited is usually the only version that makes business sense. If you break the contract, damage property, or infringe someone's rights through your own work, paying for that risk is fair. Covering losses caused by the other side's conduct, bad instructions, or shared fault is a different deal entirely.
The practical question is simple. Can you control the risk, predict the cost, and insure against it? If the answer is no, the clause is drifting into dangerous territory.
Why the labels matter in real life
Broad indemnity is the toxic version because it can make you pay for a mess you did not create. A clause tied to anything “arising out of” the project can sweep in claims where your role was minor, indirect, or just adjacent. For a small business owner, that kind of wording creates exposure you cannot price into the job without either raising your rates or accepting that one dispute could wipe out the profit from several projects.
Intermediate indemnity sounds more balanced, but it still deserves a hard read. These clauses often leave you carrying a large share of the risk unless the contract clearly carves out the other side's negligence, misconduct, or bad instructions. If those carve-outs are missing, “intermediate” can still be expensive enough to hurt.
Limited indemnity is the version worth defending in negotiations. It ties your obligation to your own actions and usually gives you a fighting chance to assess the risk before signing. That is what a fair clause should do.
Use this quick filter when you review the language:
- Safer wording: limited to your own breach, negligence, or specific misconduct
- Riskier wording: triggered by anything “related to” or “arising out of” the agreement
- Most dangerous setup: broad trigger language, a duty to defend, and no liability cap
If the other side wants you to take broad indemnity risk, treat that as a pricing issue, not a drafting footnote. More risk should buy you more money, tighter scope control, or both.
Many contracts present indemnity as boilerplate. For a large company, that may be routine. For an individual signer, it can be the clause that decides who absorbs the financial hit when a deal goes sideways.
Real-World Examples in Your Contracts
Freelance client agreement
Risky version
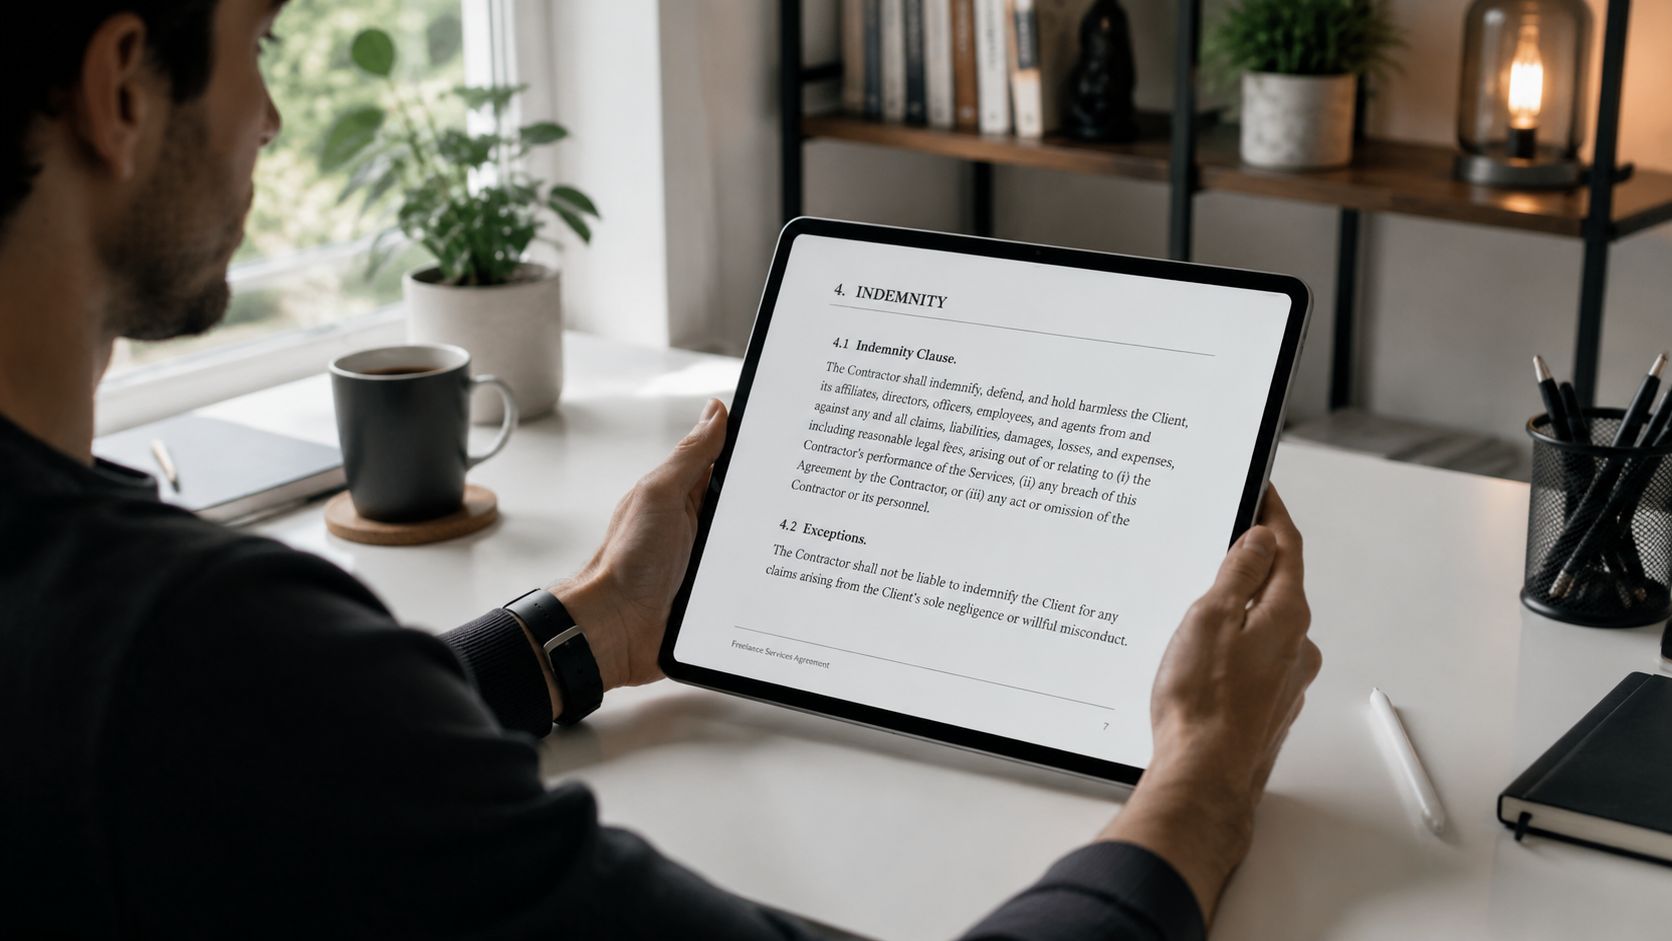
Contractor shall indemnify, defend, and hold harmless Client from any and all claims, damages, liabilities, costs, and expenses arising out of or related to Contractor's services under this Agreement.
Safer version
Contractor shall indemnify Client only for third-party claims directly caused by Contractor's breach of this Agreement or Contractor's knowing infringement of a third party's intellectual property rights. Contractor will not be responsible for claims caused by Client materials, Client instructions, or Client modifications.
The first version is common because it's easy for the client. It's terrible for the freelancer because “related to” reaches far beyond things you controlled. The safer version narrows the trigger and excludes client-caused problems.
Apartment lease
Risky version
Tenant agrees to indemnify and hold Landlord harmless from all claims, losses, and liabilities arising from or in connection with Tenant's occupancy of the premises.
Safer version
Tenant agrees to indemnify Landlord only for third-party claims directly caused by Tenant's negligence or willful misconduct within the premises. This obligation does not apply to claims resulting from Landlord's negligence, building conditions outside Tenant's control, or common-area issues.
A tenant shouldn't casually accept liability for every claim “in connection with” living in a unit. That phrase can rope in events the landlord should handle, including building maintenance failures or shared-space conditions.
SaaS subscription
Risky version
Customer will indemnify, defend, and hold harmless Provider against any claims arising out of Customer's use of the Services.
Safer version
Customer will indemnify Provider for third-party claims directly caused by Customer's unlawful use of the Services or Customer's content, excluding claims caused by Provider's platform, security failures, documentation, or instructions.
Software contracts are full of hidden allocation choices. A broad customer indemnity can make you responsible for things caused by the vendor's product design, defaults, or documentation.
Three edits improve almost every one-sided example above:
- Replace broad connectors: swap “arising out of or related to” for “directly caused by.”
- Limit the claim type: focus on third-party claims, not every conceivable dispute.
- Add exclusions: carve out the other party's materials, instructions, negligence, and misconduct.
Fair indemnity language matches control. If you can't prevent the problem, you shouldn't be the automatic payer.
Indemnity Red Flags and How to Spot Them
The fastest way to review an indemnity clause is to hunt for a few bad phrases and missing limits. If you find several in the same paragraph, slow down.
Words that should make you slow down
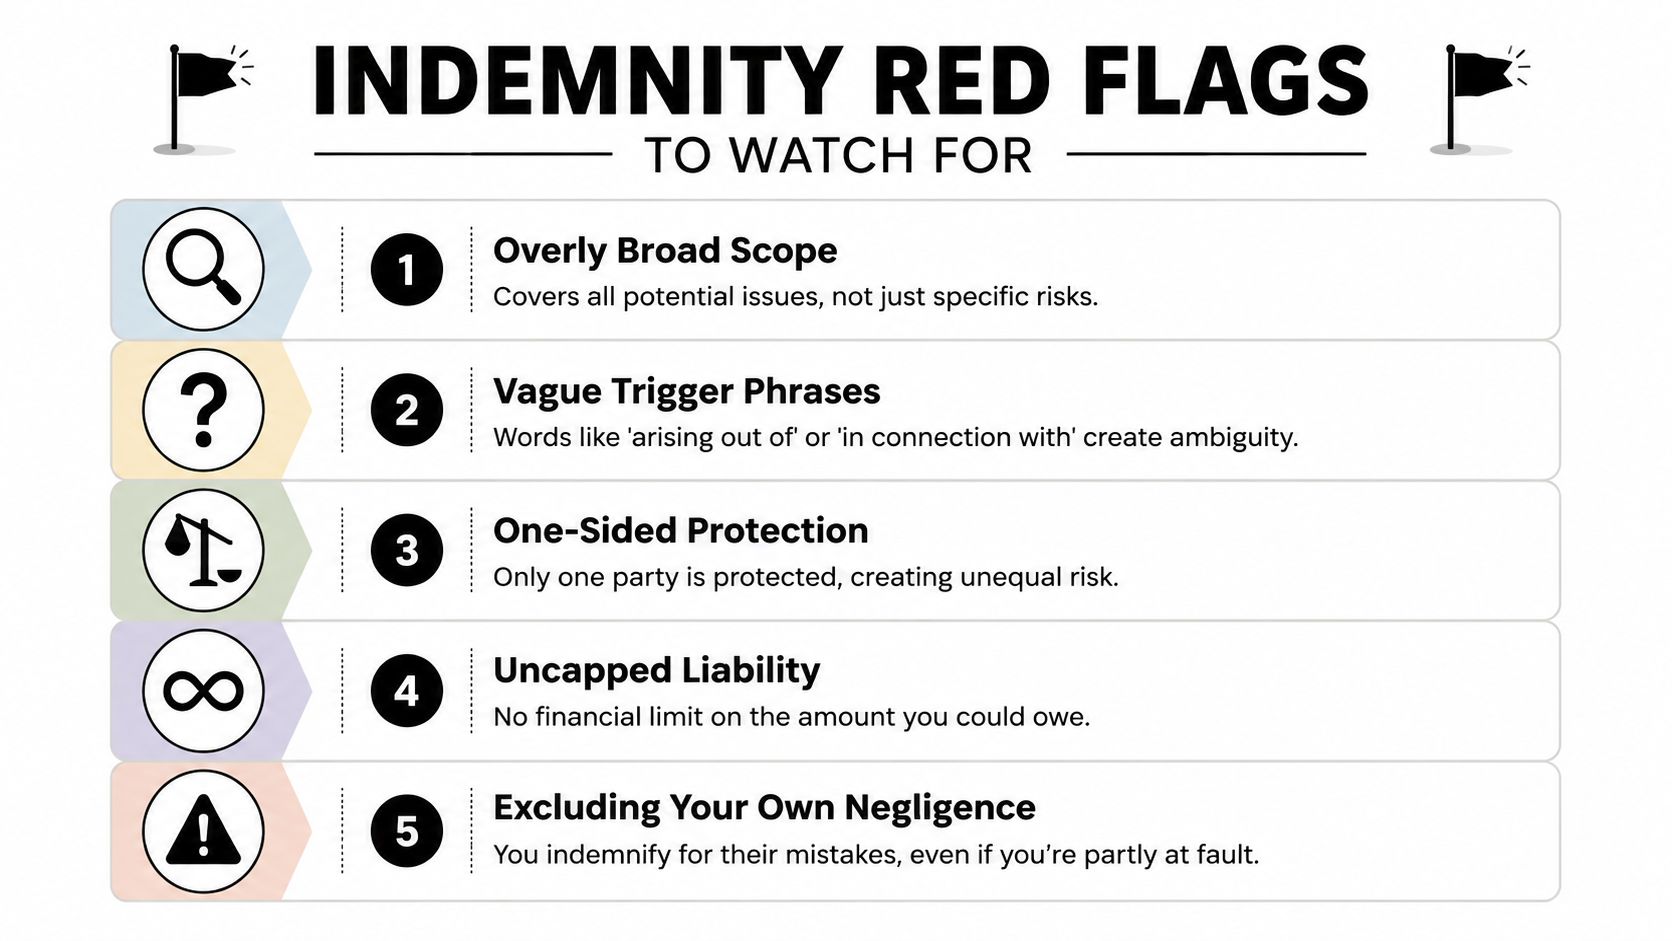
Ironclad notes that broad phrases like “any and all claims” can create unlimited liability exposure, and that negotiators commonly try to narrow coverage, add liability caps, and set 3 to 5 years as time limits for indemnification obligations according to Ironclad on broad indemnity wording and common limits.
Those are the red flags that matter in practice:
“Any and all claims” This is the contractual version of overpacking. It pulls in more than is typically intended or assumed.
“Arising out of” or “in connection with”
These phrases often widen the link between your conduct and the claim. You want tighter wording.One-way protection
If only one side gets indemnified, ask why. In many deals, each party should cover harm caused by its own conduct.No cap and no time limit
If there's no financial boundary and no end date, your exposure is hard to price and harder to live with.
A practical review checklist
When I review indemnity language for smaller clients, I'm usually looking for missing guardrails more than dramatic wording. Dangerous clauses often sound polished. Their problem is what they leave open.
Use this checklist:
- Check the trigger: Is it tied to your breach or negligence, or to anything merely connected to the contract?
- Check who caused the problem: Does the clause wrongly make you pay for the other party's mistakes too?
- Check defense language: If you must defend, when does that duty start and who controls counsel?
- Check survival: Does the clause end after a defined period, or does it keep going without a clear stop?
- Check exclusions: Are client instructions, landlord obligations, or vendor-caused failures carved out?
If a contract has several of these issues, read a broader guide to understanding contract traps before you sign anything. Indemnity problems rarely travel alone. They often sit next to liability caps that protect only the other side, auto-renewals, fee-shifting, or weak termination rights.
How to Negotiate a Safer Indemnity Clause
A client sends over a contract on Friday afternoon. The fee looks good, the start date is close, and then you hit the indemnity clause. It says you will cover losses, claims, damages, and legal fees tied to the project. If you sign it as written, you may be taking on a risk that is far bigger than the deal itself.
The goal is not to win a drafting contest. The goal is to make sure your financial exposure matches what you can control, what you are being paid for, and what your insurance might cover. That is how experienced parties handle this clause.
A safer indemnity clause usually does five things. It ties your responsibility to your own breach, negligence, or misconduct. It limits the clause to third-party claims. It excludes losses caused by the other side's instructions, materials, or mistakes. It fits under the contract's liability cap unless there is a specific reason not to. It ends after a defined period instead of hanging over you forever.
Better fallback positions than just saying no
A broad objection often gets ignored. A specific revision is easier for the other side to accept because it sounds commercial and measured.
Try these fallback positions:
- Narrow the trigger: Replace vague phrases like “arising out of” or “related to” with “to the extent directly caused by.”
- Limit it to third-party claims: Indemnity is most reasonable when it deals with outside claims, not ordinary disputes between you and the client.
- Make it mutual if both sides create risk: If each party provides materials, instructions, access, or services, each side should stand behind its own conduct.
- Tie it to the liability cap: Otherwise, a capped contract can still leave you with uncapped indemnity exposure.
- Add a survival period: A clear end date makes the risk easier to price and easier to insure against.
For a broader playbook, these contract negotiation strategies help when the other side says the wording is “standard.”
One practical point matters here. Small businesses and freelancers often feel pressure to accept boilerplate language because they are not in-house counsel. That is the wrong benchmark. The better benchmark is whether the clause makes business sense for this deal.
Practical Language for Your Email
Use language that shows you are taking responsibility for your part, not volunteering to insure the whole project.
“I'm happy to stand behind losses to the extent directly caused by my breach, negligence, or misconduct. I can't accept responsibility for claims outside my control, so please revise this clause to apply only to third-party claims and exclude issues caused by your materials, instructions, or negligence.”
That works because it does three jobs at once. It signals reasonableness. It narrows the trigger. It puts the focus where it belongs, on control and fault.
If the other side pushes back, ask a plain business question: “What specific risk do you need me to cover here?” That question often exposes whether the clause is protecting against a real concern or just shifting every possible cost downhill to the smaller party.
A short explainer can also help in live conversation:
If they refuse every edit, decide based on numbers, not pride. Compare the contract value to the downside if a claim lands. For a freelancer, tenant, or small business owner, the safest deal is often the one where the clause is boring, narrow, and clear.
Frequently Asked Questions About Indemnity Clauses
Can I just cross it out
Sometimes, yes. Often, no.
If the contract is low stakes and the other side used a generic template, striking the clause can work. In bigger deals, they'll probably push back. A smarter move is usually to revise it rather than delete it entirely. Narrow the trigger, remove the duty to defend if possible, and add exclusions for the other party's conduct.
Is indemnity the same as insurance
No. Insurance is a policy you buy from an insurer, subject to coverage terms, exclusions, deductibles, and claim procedures. Indemnity is a promise you make in the contract itself.
They can interact, but they are not interchangeable. You can have insurance and still owe more than your policy covers. You can also have an indemnity obligation for something your insurance won't cover at all.
Insurance may help fund a loss. Indemnity decides who is on the hook for the loss in the first place.
Are these clauses always enforceable
Not automatically.
Enforceability depends on the wording, the facts, the governing law, and the type of contract. Some states treat “indemnify” and “hold harmless” as synonyms, while others draw distinctions, and the treatment of broad, intermediate, and limited language can also vary as discussed earlier. That's one reason precision matters so much. Sloppy language creates real uncertainty.
If the clause is broad, unclear, or seems to make you responsible for the other party's own misconduct, get legal advice before signing.
What should I focus on first if I'm in a hurry
Read the indemnity sentence with a marker on five phrases:
- Who pays
- What triggers it
- Whether you must defend
- Whether there's a cap
- When it ends
If you can't find clear answers to those five points, the clause needs work.
What's a fair version for most small deals
A fair starting point is usually this idea: each side indemnifies the other only for third-party claims directly caused by its own breach, negligence, or specific misconduct, with clear exclusions and a defined survival period. The exact wording depends on the contract, but that structure is much safer than broad boilerplate.
If you want help reviewing contract language before you sign, Redline makes it easier to catch indemnity clauses, liability traps, and other buried terms in plain English. It's built for people without legal teams, so you can upload a contract, see risky language flagged line by line, and get a clearer sense of what deserves pushback.
Keep reading
10 Contract Negotiation Strategies for 2026
Master contract negotiation strategies for 2026. Learn to prioritize terms, frame asks, and spot risks in leases, job offers, and more with these 10 tips.
84-Month Auto Loan: The 7-Year Math the Dealer Doesn't Want You to See
22.9% of new-car loans now run 84 months. The interest cost, the negative-equity timeline, and the three scenarios where a 7-year loan actually pencils out.
A Guide to Your Remote Worker Agreement
Draft, review, and negotiate a remote worker agreement with confidence. Our guide covers key clauses, tax issues, red flags, and how to spot hidden risks.
ACV vs Replacement Cost: The Depreciation Math, the 24-Month Rule, and the Roof-Schedule Trap That Pays $4,200 on a $22,000 Roof
Roof claim came in at 25% of the quote? Here's the ACV vs replacement cost math, the 24-month rebuild rule, and the roof-schedule endorsement that quietly cuts your payout.
AI Contract Review: Your Secret Weapon Against Bad Deals
Learn how AI contract review works, what risks to watch for, and how to use it to spot unfair clauses in leases, job offers, and more. A guide for 2026.
Amazon Flex Contractor Terms: Block Forfeiture, Cargo Indemnity, and the $61.7M Tip-Skim
The block-forfeiture clause that docks pay for one missed block. The cargo indemnity that survives Amazon's app routing errors. The FTC v. Amazon Flex tip-skim settlement and what is still in the contract.
Anti-Concurrent Causation: The Insurance Clause That Denies Hurricane Wind Claims for Flood Reasons, and the 4 States That Refuse to Enforce It
Hurricane wind blew off the roof. The carrier denied the whole claim citing flood. Here's the anti-concurrent causation clause, the 4-state carve-out, and the Helene/Milton denial pattern.
Arbitration Clause Meaning: Know Your Rights
Understand the arbitration clause meaning before you sign. Learn your rights, spot risky terms, and negotiate contract changes effectively.
As-Is Used Car Sale: What 'No Warranty' Actually Lets the Dealer Get Away With
The Buyers Guide on the window has two versions. The one with 'AS IS — NO WARRANTY' checked still doesn't do what most dealers say it does. The state list, the federal floor, and the 90-day rule.
Auto Insurance Contract Red Flags: The Five Lines That Decide Whether You Walk Away Whole
The state minimum is a five-minute conversation, not real coverage. Stacked vs unstacked UM, diminished value, limited tort, and the comparative-fault math that decides what you actually recover.
Auto Loan Contract Red Flags: The Seven Shapes
Seven patterns in every auto loan contract: APR disclosures, F&I add-ons, trade-in math, arbitration, repossession, and the federal shield most buyers don't know.
Best AI Contract Review Apps in 2026: An Honest Comparison
A side-by-side look at the consumer AI contract review apps in 2026. Redline, Justee, Contract Crab, DocuSign Iris. Pricing, what each does well, what it skips.
Buyer's Agent Agreement Post-NAR Settlement: The Four Lines That Are Now Negotiable
Post-NAR settlement, the buyer-broker agreement is now required and now negotiable. The four lines to fight: compensation rate, exclusivity term, property scope, and the seller-pays gap.
Cap Cost Reduction on a Lease: When $3,000 Down Disappears
The $3,000 due at signing on a lease ad is mostly cap cost reduction. Here is what it actually buys, when it vanishes, and the handful of states where it can pay for itself.
Car Lease Red Flags: 5 Tricks Dealers Use to Pad Your Monthly Payment
Five car lease tricks that quietly add thousands to your monthly payment. Real F&I clause language, the federal disclosures that don't apply, and how to push back.
CareCredit Deferred Interest: The Retroactive 26.99% APR Most Cardholders Don't See Coming
CareCredit's deferred interest is not 0%. It is 0% only if you pay the entire balance by the promotional end date. Miss it by a day and the full balance gets billed back at 26.99% from the original purchase date. The CFPB $34.1M action, the math, and the fix.
Cell Phone Early Termination Fees, Decoded: What You Actually Owe
What carriers really charge to leave early, why your device installment loan is the new ETF, and how to switch carriers without paying twice.
Contract Red Flags: The Five Shapes Every Bad Clause Takes
Every bad contract clause fits one of five shapes. Real legalese, severity tiers, and what changed when the FTC withdrew three consumer-protection rules in 2026.
Contract Termination Clause: Your 2026 Guide to Exiting
Understand the contract termination clause before you sign. Our guide explains termination for cause, for convenience, and how to spot costly red flags.
Contracts for Small Business: Your Essential Guide
Master contracts for small business. Our guide covers essential agreements, critical clauses, and red flags to protect your venture. Avoid costly mistakes.
Credit Card Agreement: A Plain English Guide for 2026
Don't sign that credit card agreement yet. Our guide decodes the fine print, flags hidden fees and red flags, and shows you how to protect your money.
Dealer Add-Ons, Decoded: What's on the Sticker That Wasn't on the Window
GAP, VSC, paint sealant, nitrogen tires, VIN etch. The ten-times markup, what to cancel, and the FTC enforcement actions reshaping dealer pricing in 2026.
Dealer Doc Fees, Decoded: $85 in California, $800 in Maryland, Uncapped Almost Everywhere Else
17 states cap the doc fee. 33 don't. Florida and Georgia routinely charge $1,000+. Here's what the fee actually covers, where it's capped, and the OTD line that ends the conversation.
Deferred Interest Credit Cards: Your 2026 Guide
Understand deferred interest credit cards. Learn how retroactive interest works, spot red flags, and avoid costly 'no interest' traps. Be wise before you sign.
Do You Get Your Deposit Back If You Don't Sign the Lease?
Denied, or the landlord backed out? You should get it all back. Changed your mind? It depends on the receipt. When a holding deposit is refundable, plus a demand letter.
DoorDash Independent Contractor Agreement: What 'I Agree' Actually Signs You Up For
The five clauses every dasher e-signs without reading. Mandatory arbitration with a 30-day opt-out, deactivation at sole discretion, vehicle indemnity, and the FAA Section 1 question after Bissonnette.
Effective Insurance Policy Review Guide for 2026
Conduct an effective insurance policy review in 2026 with our guide. Spot red flags, understand coverage gaps, and ensure robust protection.
Employment Contract Review: A Step-by-Step Guide
Don't sign yet. This step-by-step employment contract review guide walks you through key clauses, red flags, and negotiation tactics to protect your career.
Flood Insurance NFIP Red Flags: The Four Coverage Gaps That Pay Zero on a $40K Loss
NFIP caps at $250K dwelling / $100K contents. Basement contents excluded entirely. 30-day waiting period. Risk Rating 2.0 doubled some premiums. Private flood insurance often beats it.
Freelance Contract Red Flags: The Eight Clauses That Eat Your Margin
Eight clauses that quietly turn a freelance gig into unpaid work, lost IP, or personal liability. Real legalese, severity tiers, and the state laws that protect freelancers in 2026.
Freelance Isn't Free Act: The $800 Threshold, the 30-Day Default Rule, and the Doubling-Damages Math That Makes a $4,000 Invoice Worth $8,000 + Attorney's Fees
Client ghosted on the invoice. Here's the $800 threshold, the 30-day default rule, the doubling damages math, and the four state laws that turn a $4K unpaid invoice into $8K plus attorney's fees.
Hidden Apartment Fees: What's Legal, What's a Junk Fee, and How to Push Back
The field guide to hidden apartment fees in 2026. What the FTC just fined Greystar and Invitation Homes for, the clause language to grep your lease for, and the fees you can actually push back on.
HOA Covenant Traps: The Three Clauses Buyers Miss in the 240-Page CC&Rs Binder
Special assessment authority, architectural review power, and selective enforcement. The three HOA covenant traps that cost the most after closing, with the documents to demand before signing.
HOA Special Assessment Rules: What to Know Before You Pay
Understand HOA special assessment rules before you get a surprise bill. Learn about limits, notice requirements, voting, and your rights as a homeowner.
Holding Deposit vs Security Deposit: What You Are Actually Paying
A holding deposit and a security deposit are two different legal instruments with different refund rules. A plain-English decision tree, the rollover clock, and where landlords get caught conflating the two.
Home Buying Red Flags: The 10 Traps in the Documents Between Offer and Keys
The ten home-buying red flags hiding between your accepted offer and the closing table. Real clause language, the federal disclosures that protect you, and what to negotiate before signing.
Home Contractor Contract Red Flags: The Mechanic's Lien Clause, the 10% Retainage Rule, and the Three-Day FTC Cooling-Off Right
Contractor handed you a one-page contract he wrote himself? Here's the mechanic's lien clause, the 10% retainage rule, and the FTC Cooling-Off Right that doesn't appear on his form.
Home Warranty Plans: The Three Denial Patterns and the State AG Actions That Prove the Pattern
Home warranty companies deny claims using three patterns: lack of maintenance, pre-existing condition, and coverage caps. State AGs have sued. Here are the denial patterns and the small-claims path.
How Early Termination Fees Actually Work (and When Landlords Can't Charge Them)
Early termination fees in residential leases. What's typical, when the fee isn't enforceable, and the federal and state laws that can cancel it entirely.
How Early to Renew a Lease: State Notice Rules and the Wait-30-Days Move
When to renew your lease, when to wait, and how to counter an early renewal offer with a rent increase. State-by-state notice rules and the negotiation script that works.

How Far in Advance Can You Sign a Lease? The 60 to 90 Day Window and What Actually Locks
How far in advance you can sign a lease, what locks at signing, and the holding-deposit trap that costs renters real money. Plain-English playbook with state-by-state cues.
How to Actually Cancel a Gym Contract (Without Paying for a Year You Won't Use)
The clauses gyms use to keep you paying after you quit, what your state law says about them, and the exact words to put in a cancellation letter.
How to Break a Lease: The 7 Legal Exits and How to Negotiate the Rest
A renter's guide to breaking a lease without owing thousands. The seven legal exit ramps, the duty-to-mitigate map, and the negotiation moves that work even when nothing protects you.
How to Calculate Prorated Rent: Three Methods, Three Different Answers
How to calculate prorated rent three ways, with real numbers for each, so you can check the landlord's move-in or move-out charge before you pay it.
How to Cancel a Subscription When They Make It Impossible
When the cancel button is hidden behind a phone tree, here's the playbook. State laws, the chargeback path, and the letter that creates a paper trail.
How to Get Out of an Auto-Renewal Contract: The Five-Step Escape
A step-by-step guide for getting out of an auto-renewal contract, the chargeback and state-law leverage that works when the cancellation window closed, and the four templates you can send today.
How to Get Your Security Deposit Back (Without Suing Your Landlord)
A renter's playbook for getting your full deposit back. The 21-day clock, the bad-faith multiplier, and the demand letter that makes corporate landlords pay up in 10 days.
How to Redline a Contract: A Practical Walkthrough
Learn how to redline a contract with confidence. This guide covers reading the document, spotting risky clauses, drafting changes, and negotiating like a pro.
Indemnification Clauses, Explained: What 'Hold Harmless' Actually Costs You
An indemnification clause turns a small contract into an unlimited bet. Here's what the four flavors actually mean, why "duty to defend" is the part that hurts, and how to negotiate it down.
Independent Contractor vs Employee: Why Your 1099 Doesn't Decide It
A 1099 doesn't make you a contractor. The federal six-factor test, the state ABC test, and the contract clauses that quietly signal you're misclassified.
Instacart Shopper Agreement: The Tip-Baiting Clause and Three Other Traps
The clause that lets customers cut your tip 24 hours after delivery. The non-engagement metric. The chatbot-only deactivation appeal. The four mechanics inside the Instacart full-service shopper contract.
Insurance Claim Denied: The 5 Reasons Carriers Use, the 30-60-90 Day Appeal Timeline, and When to File with the Commissioner
Got a denial letter for a homeowners claim. Here's the 5-reason taxonomy carriers actually use, the appeal timeline, and the state UPPA your insurer doesn't want to invoke.
Insurance Policy Red Flags: The Five Clauses That Decide If Your Claim Pays
53% of Hurricane Helene claims denied. The five clauses that decide whether your insurance pays or stalls: exclusions, named-perils, ACV, anti-concurrent causation, and the appraisal clause.
Is Your Non-Compete Actually Enforceable? A Plain-English Guide
What non-competes really say, why most are narrower than they look, and what your old offer letter is worth now that the FTC ban has been withdrawn.
Landlord Red Flags: 12 Warning Signs to Catch Before You Sign
Landlord red flags to catch before you sign: what they say before and during the viewing, what hides in the lease, and how to check a landlord in 15 minutes.
Lease Mileage Overage: What 14,000 Extra Miles Costs at Turn-In
Lease mileage overage is $0.15 to $0.30 a mile at turn-in. Per-captive rates, the buy-upfront break-even, and the 14k mi/yr point where leasing stops working.
Lease Start Date vs Move-In Date: Which One Starts Your Rent?
Your lease start date is when rent starts. Your move-in date is when you get the keys. Who pays for the gap, and what to do if the unit is not ready.
Lease vs Buy at 7% APR: The Math That Changes Everything
Most lease vs buy posts use 4% APR and lease wins. At May 2026's real 7% auto-loan rates, the answer flips at 5 years of hold. Three scenarios, full math.
Legal Document Scanner: The AI Guide to Contract Risk
What is a modern legal document scanner? Learn how AI tools analyze contracts for hidden risks in leases, job offers, and NDAs before you sign.
Life Insurance Beneficiary Traps: The Five Designations That Decide Who Gets the Money
Ex-spouse not removed, per stirpes wrong default, ERISA preemption, the slayer rule. Five beneficiary traps that pay the wrong person, and the five-minute review that fixes them.
Lyft Driver Agreement: Period 1, Period 2, Period 3, and the Insurance Gap You Pay For
The Lyft Driver Agreement names three periods. Coverage only kicks in fully during Periods 2 and 3. Period 1 is your personal insurance, and most personal policies exclude commercial use. The contract clauses behind the gap.
Master Your Car Rental Agreement: 2026 Insider Guide
Stop overpaying. Learn to decode your car rental agreement, spot hidden fees, and understand liability before you drive away in 2026.
Mastering Payment Terms in Contracts
Avoid bad payment terms in contracts. Spot red flags, negotiate like a pro, and ensure timely payment every time. Practical guide.
Money Factor Markup: How Dealers Hide $864 in Your Lease
The money factor on your lease worksheet is two numbers added together. The captive lender's buy rate, plus the dealer's markup. Here's how to separate them.
Mortgage Closing Disclosure Red Flags: The TRID Tolerance Buckets and the 60-Day Cure
TRID gives you 3 business days to compare the Closing Disclosure to the Loan Estimate. Zero-tolerance fees that increased are recoverable as a cure within 60 days. The federal rule, the cure script, the buckets.
Moving Company Contract: The 110% Rule, the 60-Cents-Per-Pound Trap, and the Hostage-Load Federal Violation
The estimate said $3,400. The driver wants $5,200 to unload. Here's the federal 110% rule, the four required documents, and why hostage loads are a federal crime.
NDA Explained in Plain English: What You're Actually Promising When You Sign
An NDA you sign at a job interview can outlast the job by twenty years. What confidentiality clauses actually do, what the Speak Out Act voided, and the four redlines worth asking for.
Negative Equity Trade-In: The $7,183 Question on Your Next Car Loan
30.9% of trade-ins are underwater. Rolling that balance into the next loan makes you 1.5x more likely to be repossessed within 2 years. The math, and the alternatives.
Normal Wear and Tear vs Damage: The Math Your Landlord Doesn't Want You to Do
A line-by-line guide to what counts as normal wear and tear, what counts as damage, and the useful-life math that turns a $1,400 carpet bill into $200.
Offer Letter Red Flags: 6 Clauses to Catch Before You Sign
Six offer letter red flags hiding in standard employment paperwork. Real clause language, the 2026 stay-or-pay laws in California and New York, and how to push back without losing the offer.
Paying a Security Deposit Before Signing a Lease: Is It Safe?
Paying a deposit before signing a lease is common and usually legal, but it is a holding deposit, not a security deposit. When you get it back and what to get in writing.
Personal Loan Agreement Red Flags: Origination Fees, Autopay Asymmetry, and the APR That Isn't
The origination fee that comes out of the principal. The autopay discount that disappears when your bank changes. The disclosed APR vs the effective APR. Four clauses every personal loan agreement hides and what TILA actually requires.
Proof of Income for Apartment Applications: What Landlords Accept
Proof of income for an apartment means pay stubs, an employment letter, tax returns or bank statements. See what to send for your case, plus the 3x rent math.
Redline vs ChatGPT for Contract Review: An Honest Comparison (2026)
Should you use ChatGPT or a dedicated app like Redline to review a contract? A side-by-side comparison of workflow, output, privacy, mobile fit, and pricing.
Rent Stabilization Laws: A Tenant's 2026 Guide
Understand rent stabilization laws in 2026. This guide explains your rights, how to check your unit's status, and spot illegal lease clauses.
Rental Scam Red Flags: How to Spot a Fake Listing Before You Pay
Rental scam red flags on Facebook, Craigslist and Zillow: the out-of-town landlord, the Zelle deposit, the fake lease, and what to do if you already paid.
Renters Insurance Coverage Traps: The Six Sub-Limits That Pay $1,500 on a $4,000 Loss
Your renters policy says $25K personal property. The fine print is six sub-limit categories at $1,000-$2,500 each. The scheduled property fix, the ACV vs RCV trap, and the roommate coverage gap.
Sample Limitation of Liability Clause: 7 Forms to Know
Find a sample limitation of liability clause for any contract. Explore 7 key examples with plain-English analysis of risks, pitfalls, and negotiation tips.
Severance Agreement Red Flags: OWBPA's 21-Day Window, the 7-Day Revocation Period, and the Three Releases You Can't Actually Waive
HR slid a 10-page severance across the table with 'sign by Friday.' Here's the OWBPA framework, the unwaivable releases, and the McLaren Macomb non-disparagement limit.
Severance Agreement Review: Get a Fair Deal
Get an expert severance agreement review. Spot red flags, negotiate better terms, and know when to get legal help before you sign.
Software Development Agreements: Negotiate Your Best Deal
Master your software development agreements. This guide reveals key clauses, hidden traps, and negotiation tactics to protect your IP and secure fair terms.
Solar Contract Red Flags: The 20-Year Trap on Your Roof
Escalator clauses, UCC-1 liens, transfer traps. What the door-to-door rep didn't show you, and the 3-day window where you can still walk away.
Storage Unit Rental Agreement Red Flags: The Lien Timeline That Auctions Your Stuff
Storage facilities can auction your unit faster than any other landlord-tenant relationship. California 14 days, Florida 5, plus contracts that expand the operator's rights to the legal maximum. The four clauses you signed.
Subscription Contract Red Flags: The Four Mechanisms That Compound While You're Not Looking
Auto-renewal, cancellation friction, unilateral ToS changes, ETFs. Why every recurring contract feels like a roach motel, and how the 2025–2026 legal landscape changes your escape routes.
Tenant Rights Security Deposit: Get Your Money Back in 2026
Understand your tenant rights security deposit. Learn about legal limits, deductions, demand letters, and how to get your money back in 2026.
The 8-Point Contract Review Checklist
Use this 8-point contract review checklist to spot red flags in liability, IP, termination, and payment clauses before you sign. For freelancers & tenants.
The Meaning of Severability: A Contract Guide for 2026
Grasp the meaning of severability in contracts. Learn what a severability clause is, its importance, and when it might not save your agreement.
Title Loan Agreement Red Flags: The 30-Day Rollover, the 300% APR, and the MLA 36% Cap
Title loans use your car as collateral. State APR caps range from 30% to 'no cap.' The Military Lending Act caps active-duty servicemembers at 36% MAPR. The agreement, the rollover trap, and the repo timeline.
Uber Arbitration Opt Out: The 30-Day Email, Word for Word, and What It Gets You
How to opt out of Uber arbitration as a driver: the exact email Uber's agreement requires, how to count the 30 days, what it changes, and how to keep proof.
Uber Driver Agreement Explained: What Tapping 'Yes, I Agree' Actually Signs
The Uber driver agreement in plain English: where to read it, what tapping I agree changes, the 30-day arbitration opt-out, deactivation, and insurance gaps.
Understanding a Quitclaim Deed: Risks & Usage in 2026
Learn about a quitclaim deed: its uses, risks, and how it differs from a warranty deed. Get essential filing steps for 2026.
Understanding the Jurisdiction Clause in Agreement
Confused by the jurisdiction clause in agreement? Learn what it means, the key risks involved, and how to negotiate it before you sign.
US Cellular Early Termination Fees After the T-Mobile Merger: What You Actually Owe
What US Cellular customers actually owe after the August 2025 T-Mobile acquisition, why your device installment loan survived the merger, and how the Keep and Switch reverse-payoff really works.
Wedding Catering Contract: The Headcount Lock, the Stacked Service Charge, and Two Other Traps
The headcount-lock date that bills you for guests who never showed. The 18 percent 'service charge' that is not the tip. The market-unavailable menu swap. Four clauses in your wedding catering contract that move real money.
Wedding DJ Contract: The Substitution Clause, the 3x Overtime, and the Equipment Indemnity
The clause that lets your booked DJ send a junior. The overtime rate that triples after midnight. The equipment-damage indemnity that makes you liable when a guest spills on the mixer. Three traps in your wedding DJ contract.
Wedding Florist Contract: The Substitution Clause That Swaps Your Peonies for Carnations
The 'florist's discretion' substitution clause. The wholesale-pricing pass-through with no cap. The setup and teardown fees below the line items. The breakage liability for rented vases. Four traps in your wedding florist contract.
Wedding Photographer Contract Red Flags: The Four Clauses Every Couple Signs Past
The non-refundable retainer most state contract law caps. The delivery window with no teeth. The copyright clause that keeps you from your own prints. The force-majeure language COVID rewrote. Four traps in your wedding photographer contract.
Wedding Venue Contract Red Flags: The F&B Minimum, the Preferred-Vendor Tax, and Three Other Clauses
The food-and-beverage minimum that stays fixed when your guest count drops. The 'preferred vendors only' clause that adds 10 to 50 percent per outside vendor. The overtime rate that triples at midnight. The five clauses to negotiate before you sign the venue.
Wedding Videographer Contract: The 12-Month Delivery Window, the Sync License, and Raw-Footage Rights
The delivery window measured in months with no SLA. The music sync-licensing exposure most couples never see. The raw-footage release the contract usually denies. Five clauses to negotiate in your wedding videographer contract.
What Is a Buyout Clause: Lease & Job Offer Guide
Discover what is a buyout clause, how it works in leases & job offers, and how to spot red flags. Our 2026 guide covers calculations, risks, and negotiation.
What Is a Force Majeure Clause: 2026 Essential Guide
Discover what is a force majeure clause, how it impacts contracts, and key elements for 2026. Spot risks before you sign.
What Is a Letter of Employment? Sample Letter and How to Get One Fast
A letter of employment is a signed note from your employer confirming your job, start date and pay. Copy a sample, request one fast, and see what gets checked.
What Is a Penalty APR? a 2026 Guide to This Costly Trap
Wondering what is a penalty APR? Learn how this hidden credit card fee works, what triggers it, and how to avoid or remove its 29.99% interest rates.
What Is a Personal Guarantee? The Sentence That Puts Your House on the Line
A personal guarantee turns your business contract into a personal one. Here's what the clause actually says, when you're really on the hook, and how to negotiate it down.
What to Look For in a Lease Agreement: 10 Red Flags
Don't sign yet. Learn what to look for in a lease agreement with our checklist of 10 clauses, red flags, and how to negotiate them before you move in.
What to Look For in a Lease Before You Sign
A national framework for reading a residential lease, with real clause language and state-by-state notes on security deposits, fees, and renewal.
When the Terms of Service Change on You: What's Enforceable, What Isn't
When a company quietly rewrites its TOS, the new terms often aren't binding. The case law is on your side, and the same clause that lets them change anything can void their own protections.
Why You Got Charged Again: Auto-Renewal Clauses, Decoded
What an auto-renewal clause means, why companies use them, and the state laws now doing the work the FTC's withdrawn click-to-cancel rule was supposed to do.
Yo-Yo Financing: When the Dealer Calls You Back After You Drove Off
The dealer calls four days later and says your financing fell through. Here's why the original contract may still bind them, and the 48 hours that decide everything.
Your Separation Agreement Template & Clause-by-Clause Guide
Get our free separation agreement template. This guide explains each clause, warns of red flags, and shows how to customize it for an amicable split.